
Key Takeaways
- Intercompany reconciliation is the process of matching, confirming, and eliminating transactions and balances recorded between two or more legal entities within the same corporate group.
- It matters because consolidated financial statements cannot legally include intercompany transactions. An unreconciled intercompany balance either overstates the group's financials or forces a manual plug at consolidation, neither of which holds up to audit.
- The process runs through five core steps: identify intercompany accounts, confirm balances between entities, investigate mismatches, post elimination entries, and reconcile the net-to-zero result.
- Intercompany reconciliation is consistently the hardest reconciliation type to scale, because it depends on two separate ledgers, often on two separate ERPs, agreeing with each other.
- Most organizations still run this process manually. A Deloitte intercompany accounting survey found 54% of organizations still process intercompany transactions manually, with limited counterparty visibility.
A transaction between a parent company and its subsidiary is real to both entities individually, but invisible to the group as a whole once the financials consolidate. Getting that invisibility to actually hold, cleanly, at every close, is what intercompany reconciliation exists to do.
A quick overview: this guide covers what intercompany reconciliation is, why unmatched balances create real consolidation and audit risk, the five-step reconciliation and elimination process, and why this specific reconciliation type is consistently the hardest one to scale as a company adds entities and ERPs.
What Is Intercompany Reconciliation?
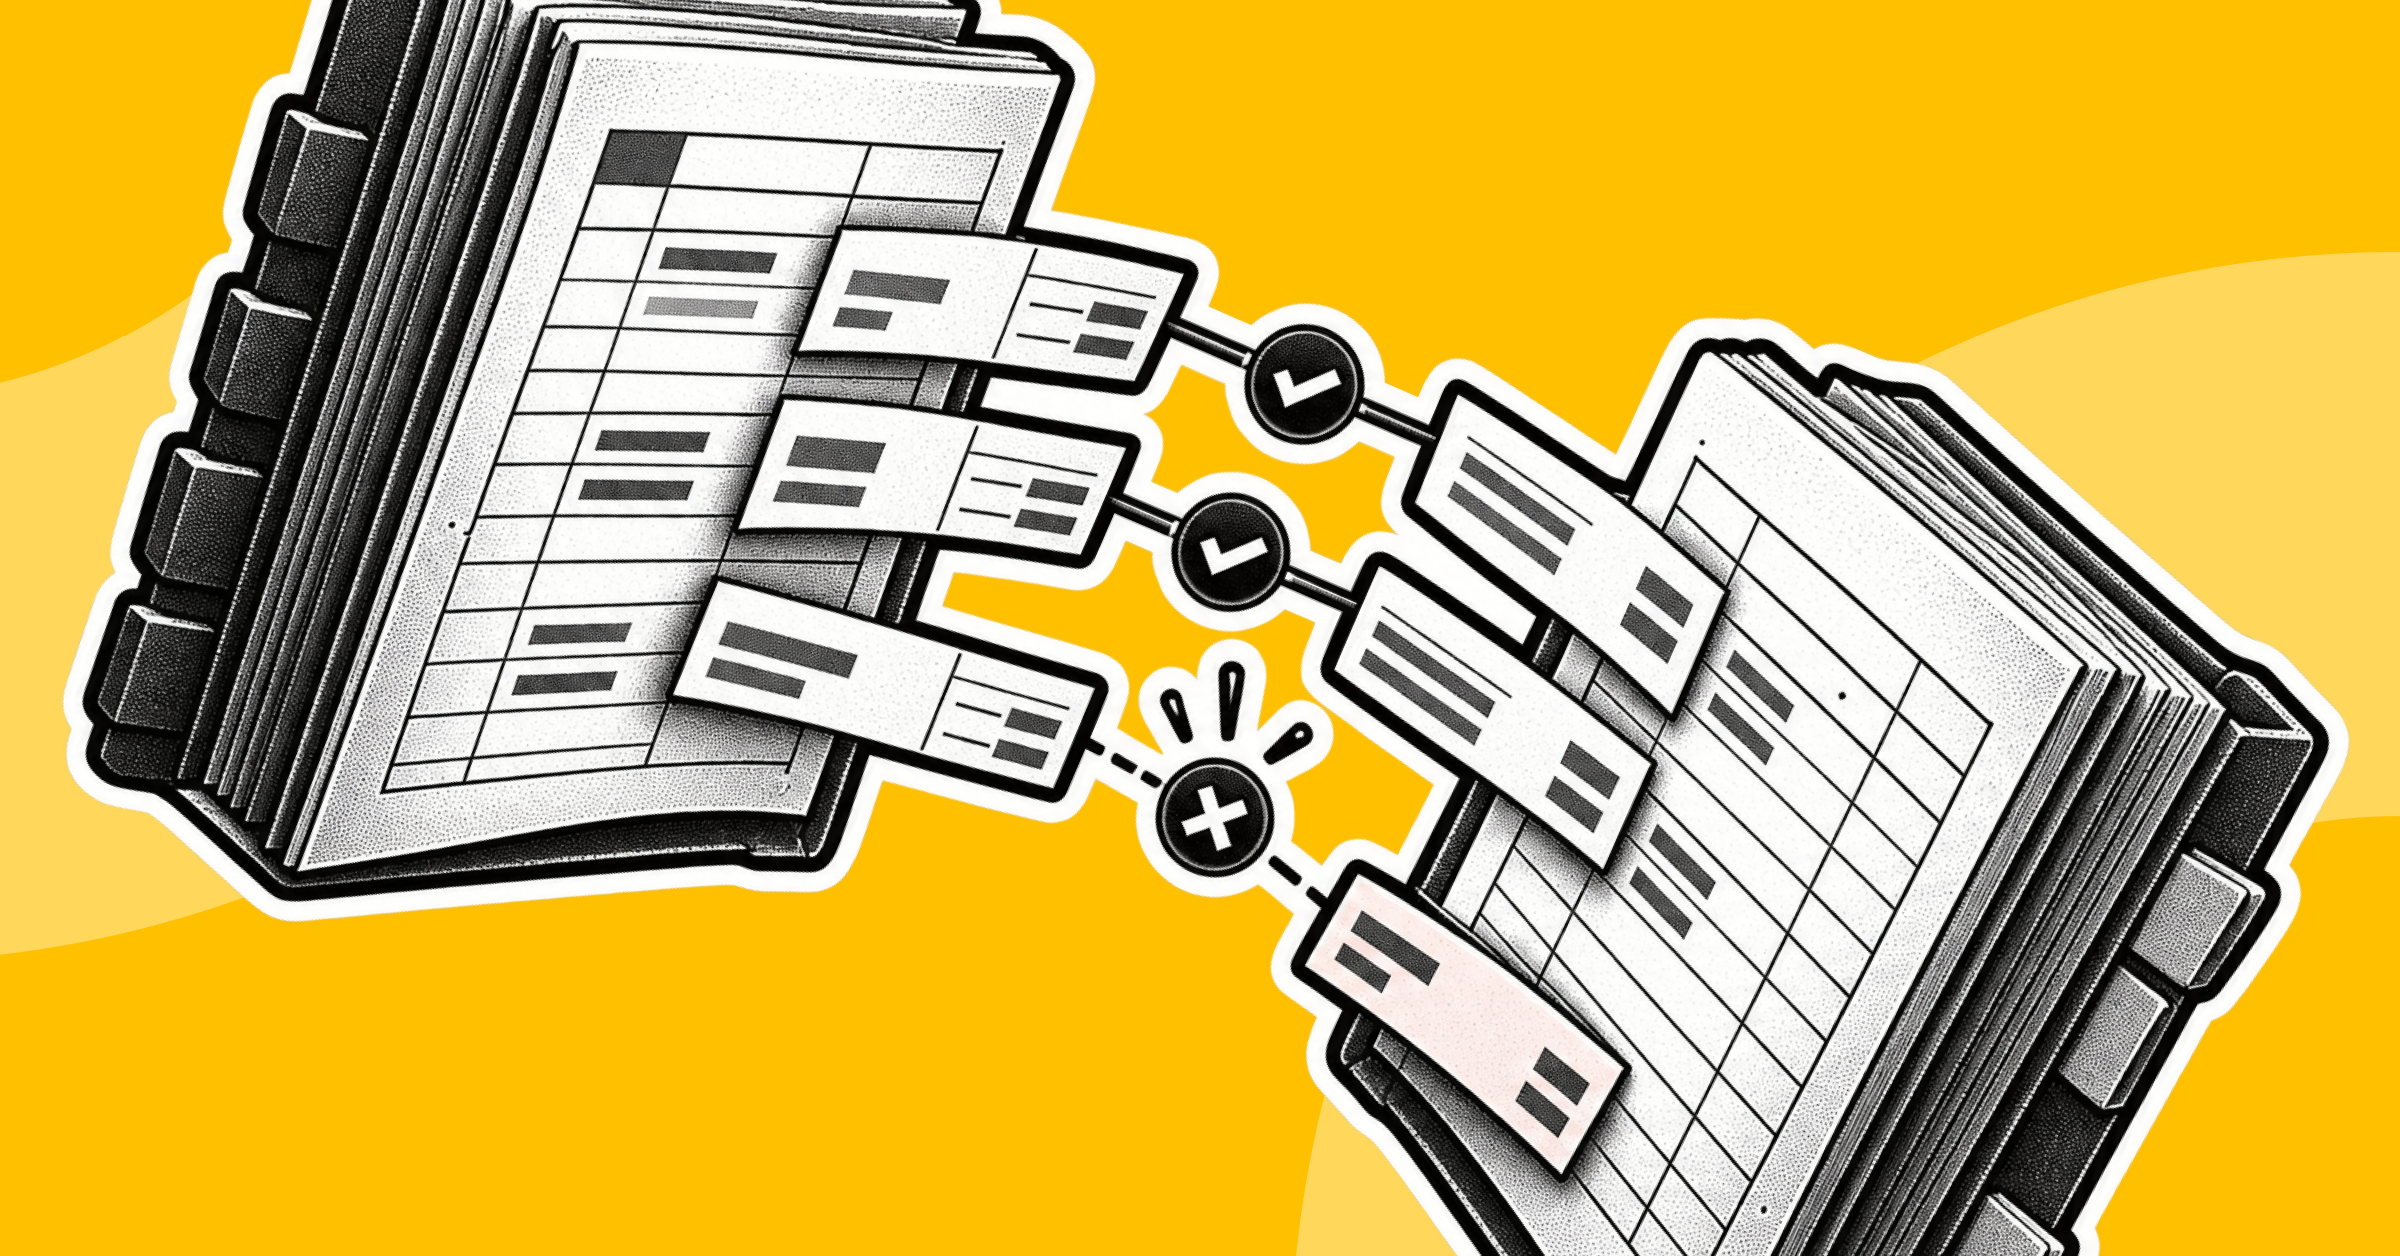
Intercompany reconciliation is the process of matching, confirming, and eliminating financial transactions and balances that occur between two or more legal entities within the same corporate group, such as a parent company and its subsidiaries, or two subsidiaries transacting with each other. The goal is to confirm both sides of every intercompany transaction agree before those balances are eliminated from the consolidated financial statements.
It's distinct from general general ledger reconciliation in one important way: it requires two independent ledgers, often maintained by different teams or on different ERPs, to agree with each other, rather than a single ledger agreeing with an external document like a bank statement. Bluecopa's own intercompany reconciliation glossary entry covers the underlying elimination mechanics in more depth.
Why Intercompany Reconciliation Matters for Consolidation and Audit
Consolidation accounting rules require that intercompany transactions be eliminated before a group's financial statements are presented, so that revenue, expenses, receivables, and payables aren't double-counted across entities. That elimination only works cleanly when both sides of the intercompany transaction actually match.
- Consolidation accuracy: an unmatched intercompany balance either gets forced to zero with a manual plug, or it flows through and overstates the group's consolidated numbers.
- Audit risk: auditors specifically test intercompany eliminations. Unreconciled or plugged intercompany balances are a recurring source of audit findings and management letter comments.
- Tax and transfer pricing exposure: intercompany transactions often carry transfer pricing implications. A reconciliation gap can obscure whether intercompany pricing was applied and recorded consistently across entities.
- Close timeline risk: intercompany is one of the last steps before consolidation, so a mismatch discovered late routinely delays the entire group close, not just one entity's books.
The Intercompany Reconciliation Process
This process sits inside the broader record-to-report cycle, since intercompany elimination is one of the last reconciliation steps before consolidated financials are produced.
- 1. Identify intercompany accounts and counterparties: map every account that carries intercompany activity across every entity, and confirm which entity is the counterparty on each side.
- 2. Confirm balances between entities: each entity confirms its recorded balance with the counterparty entity, ideally before period close rather than after.
- 3. Investigate mismatches: trace variances to their cause, commonly timing differences (one entity recorded a transaction before the other), FX translation differences, or a transaction recorded on only one side.
- 4. Post elimination entries: once balances agree, post the elimination entries that remove the intercompany activity from the consolidated view.
- 5. Reconcile to net zero: confirm the eliminated intercompany balances net to zero at the group level, and document any residual difference that couldn't be resolved before close.
The accounting mechanics behind step 4 follow established consolidation guidance, including the elimination requirements under FASB ASC 810 for consolidated financial statements.
Why Intercompany Reconciliation Is Hard at Multi-Entity, Multi-ERP Scale
Intercompany reconciliation is the reconciliation type most exposed to scale, because the number of entity pairs that need to agree grows faster than the number of entities.
- Entity-pair growth: a group with 10 entities can have up to 45 unique intercompany relationships to reconcile, not 10. Add a few more entities and that number grows sharply.
- Multiple ERPs: when entities run on different ERPs, counterparties can't simply query each other's ledger. Data has to be extracted, normalized, and compared outside either system, which is exactly the work most native ERP intercompany modules don't automate.
- Currency and FX translation: cross-border intercompany balances introduce FX translation timing differences on top of ordinary matching mismatches, adding a second variable to every variance investigation.
- Manual netting still dominates: the Deloitte survey cited above found the majority of organizations still process intercompany manually, with limited visibility into what the counterparty entity actually recorded, which is the root cause of most late-cycle intercompany surprises.
Intercompany Reconciliation Best Practices
- Confirm balances before period close, not after. Waiting until close to discover a mismatch leaves no time to investigate it properly.
- Standardize intercompany transaction coding so every entity tags intercompany activity consistently and it can be isolated for reconciliation without manual filtering.
- Give every counterparty pair visibility into the other side's recorded balance, rather than reconciling in isolation and comparing only at month-end.
- Automate matching across ERPs wherever more than a handful of entities or more than one ERP are involved, since manual cross-ERP tracing is where most delays originate.
- Document unresolved differences rather than force-plugging them, so recurring root causes are visible over time instead of hidden inside a rounding adjustment.
For a broader look at fixing the process end to end, including governance and system consolidation, see optimizing the intercompany accounting process. Teams weighing whether to buy dedicated software yet can also start with how to choose intercompany accounting software.
How Bluecopa Supports Intercompany Reconciliation
Enterprise finance teams running reconciliation across multiple entities and ERPs use Bluecopa's Samyx Recon engine, which processes over 5 million records per hour at 97 to 99% accuracy using hybrid deterministic and multi-field fuzzy matching, built specifically for cross-entity and cross-ERP matching rather than reconciliation within a single ledger. Bluecopa connects to 200+ systems, including SAP, Oracle NetSuite, and Sage Intacct. Yatra reported a 90% faster month-end close after adopting Bluecopa for reconciliation and close. Teams evaluating dedicated software for this specific problem can compare options in Bluecopa's intercompany reconciliation software guide.
Frequently Asked Questions
1. What's the difference between intercompany reconciliation and intercompany elimination?
Reconciliation is the process of confirming both entities' recorded balances agree. Elimination is the accounting step that follows, removing the matched intercompany activity from the consolidated financial statements.
2. How often should intercompany reconciliation happen?
Monthly at minimum, aligned with close. Organizations with high intercompany transaction volume or frequent cross-entity activity benefit from reconciling continuously rather than only at period-end.
3. Why do intercompany balances so often not match?
Timing differences are the most common cause, one entity records a transaction before the other. FX translation differences and transactions recorded on only one side of the pair are the next most common.
4. Can intercompany reconciliation be automated?
Most of the matching and exception-flagging can be automated, particularly across ERPs. Genuine unresolved variances, like a transaction one entity never recorded, still require manual investigation.
5. Is intercompany reconciliation required for every multi-entity organization?
Yes, for any organization that presents consolidated financial statements. Intercompany transactions cannot remain in consolidated results under standard consolidation accounting rules.