

Key Takeaways
- Most R2R cost advice stops at "automate and standardize." The useful question is narrower: what is your record to report cycle costing per journal entry and per $1,000 of revenue right now, and which lever moves that number first.
- APQC's cross-industry benchmarks put general accounting at roughly $3.50 per journal entry and $0.91 per $1,000 of revenue, with the broader R2R process around $2.30 per $1,000. Those four figures are enough to size your own gap in an afternoon.
- The single biggest swing factor is the share of journal entries posted manually. Top performers sit between 0.75% and 6%. The median is 25%. That gap is where most of the labor cost lives.
- Levers do not pay back equally. Journal entry policy and close standardization pay back in months and cost almost nothing. ERP consolidation pays back in years. Sequencing them wrong is the most common way an R2R cost program stalls.
- Cutting cost badly is worse than not cutting it. Headcount reductions ahead of process standardization, and offshoring an unstandardized close, both reappear later as overtime, contractors and audit findings.
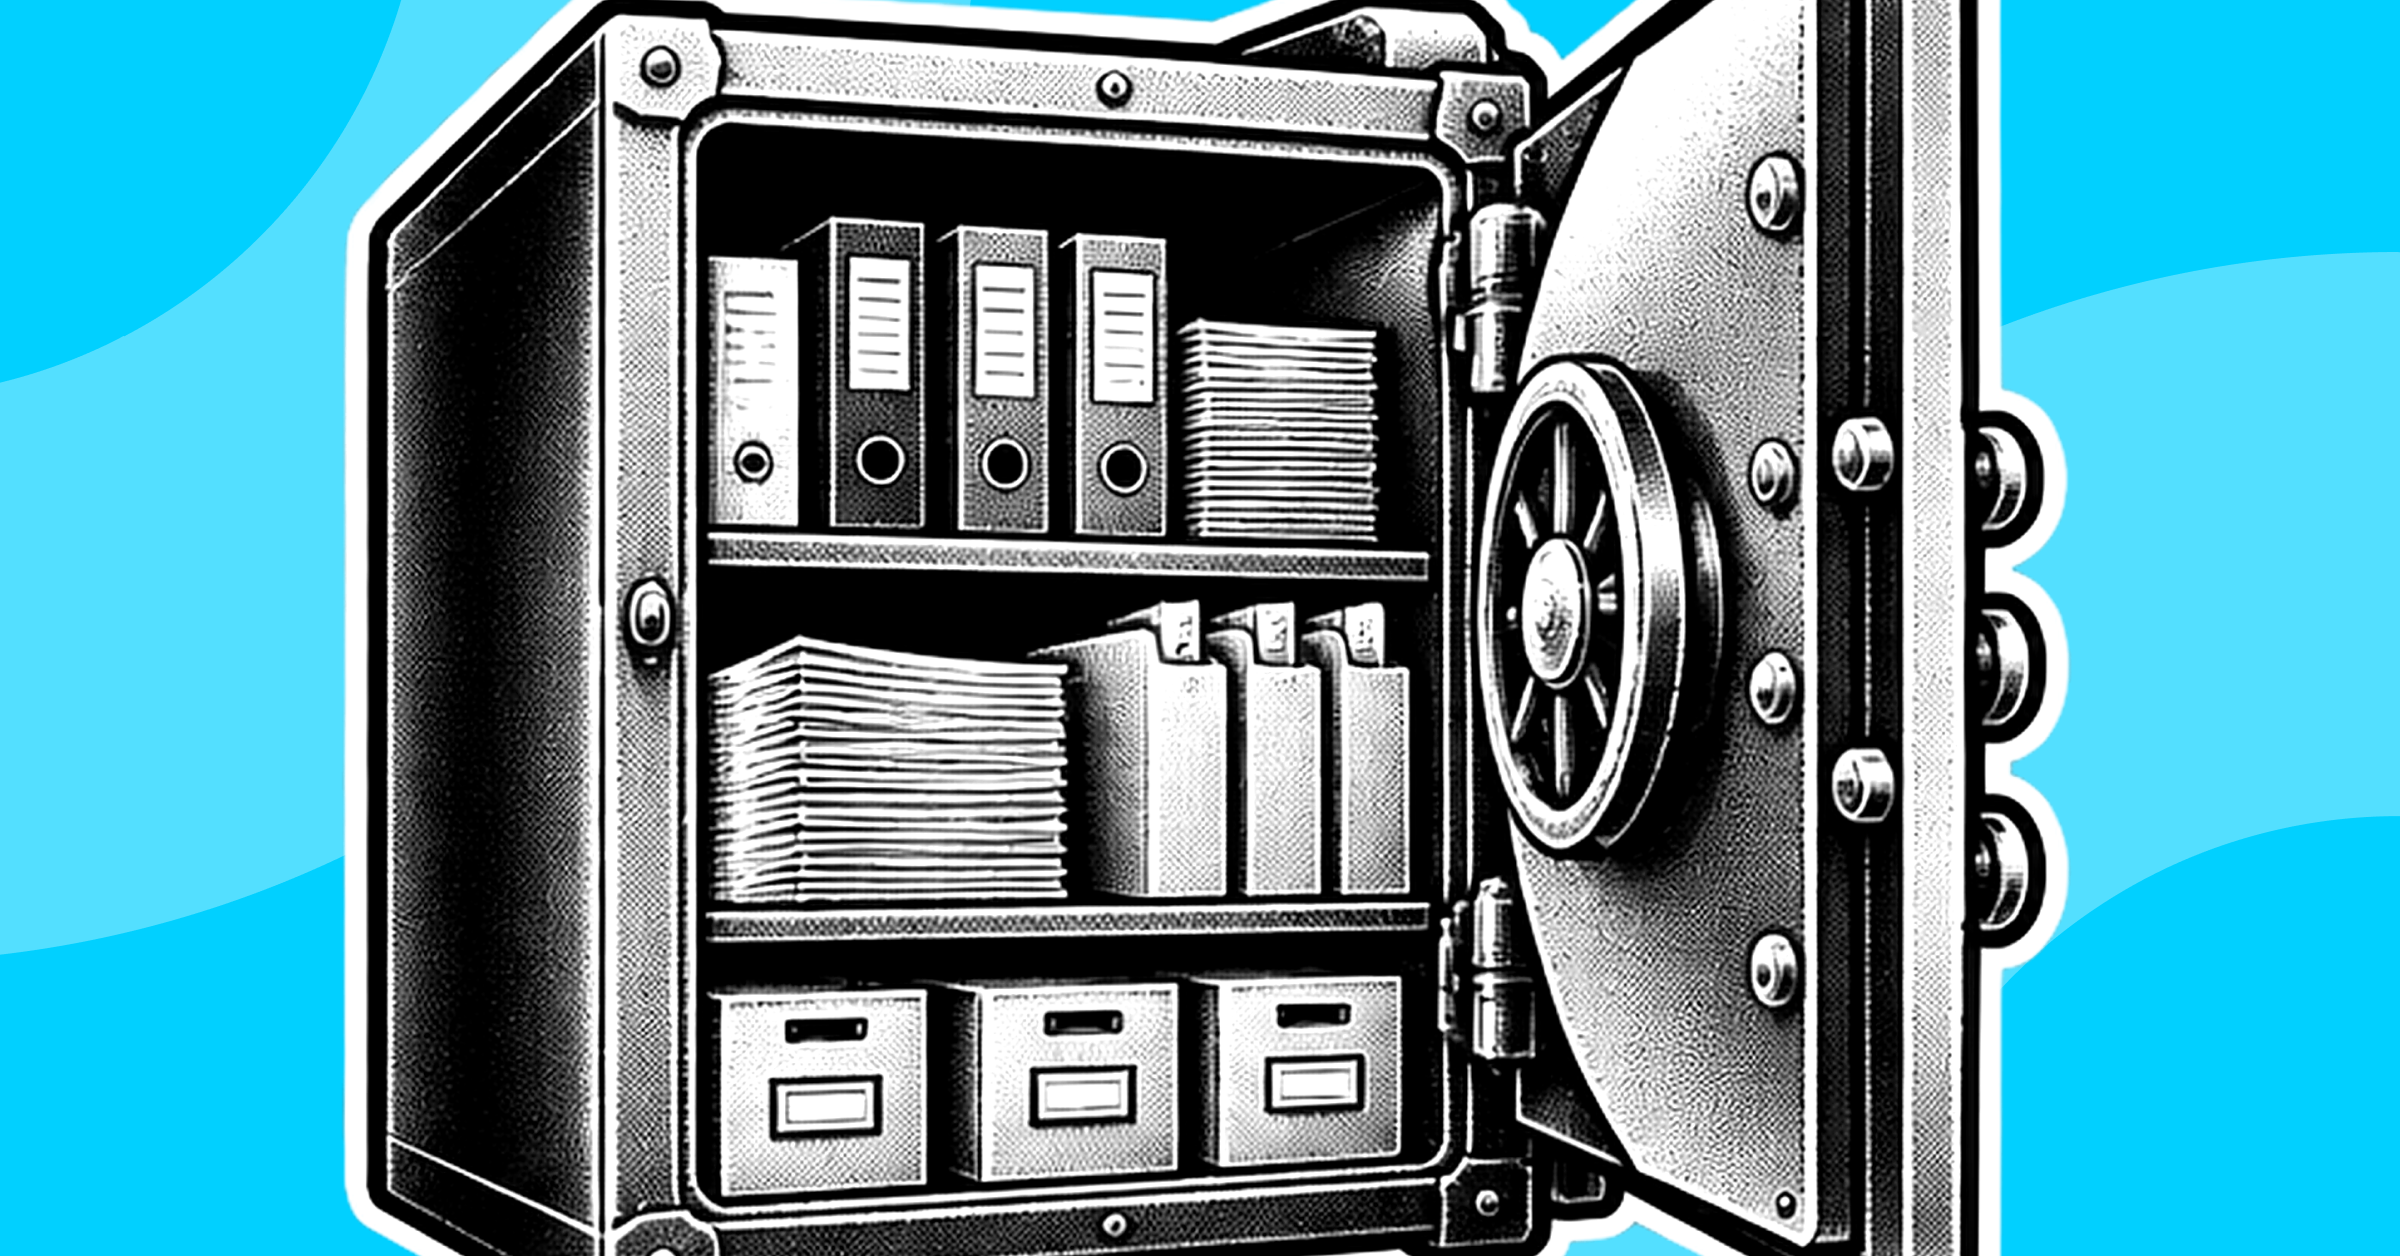
Record to report covers everything from subledger close through the consolidated financial statements, and in most enterprises it is still run on a mix of ERP modules, spreadsheets and manual review. IBM puts R2R at roughly 20% of total finance process cost, which makes it one of the larger line items a CFO can actually do something about without touching the commercial side of the business.
The problem with most cost-reduction advice on this topic is that it never gets specific. You already know automation helps. What you need is a way to work out what your own cycle costs today, which parts of it cost the most, and which fixes return money fastest. That is what this guide does: the cost drivers, the benchmark figures to measure against, a simple model you can run on your own numbers, and the levers ranked by how quickly they pay back.
How Can You Reduce Cost in the R2R Cycle?
You reduce R2R cycle cost by cutting the volume of manual work in four places: journal entries, reconciliations, exception handling, and the data preparation that feeds all three. Everything else is a variation on those four.
In practice that breaks into four families of change, roughly in the order they tend to pay back:
- Policy and standardization. Materiality thresholds on manual journals, a unified chart of accounts, one owner and one deadline per close task. This costs nothing but management attention and removes a surprising amount of work.
- Automation of high-volume, rules-based work. Recurring journal entries, bank and subledger matching, certification of low-risk accounts.
- Workload smoothing. Moving routine tasks off the month-end peak so you stop paying for overtime and temporary capacity in the same five days every month.
- Operating model and data layer. Shared services, global capability centers, and eventually ERP or data consolidation. These matter, but they are the slowest to return money.
The rest of this guide takes each of those apart.
Where R2R Cost Actually Sits
R2R cost is not the salary line of the general accounting team. It is the labor, systems and overhead needed to prepare and post journals, reconcile accounts, investigate differences, consolidate results, evidence controls and produce the reports. Most of it is labor, and most of that labor is spent on correction and coordination rather than on the accounting itself.
Before you choose a lever, break your current spend down against these drivers. The right-hand column is what you need to actually measure, not estimate.
Two of these deserve particular attention, because they are the ones finance teams consistently underestimate.
The first is exception investigation. Automating journal creation does nothing for the cost of working the same unexplained difference three months running. If your exception management has no root-cause loop, automation just produces the same exceptions faster.
The second is peak-load staffing. A close that compresses ten days of work into five does not cost the same as a close that spreads it evenly. You are paying a premium for the concentration, and it shows up as overtime, as contractor invoices, and as attrition.
What R2R Should Cost: The Benchmark Figures
APQC's Open Standards Benchmarking publishes the only widely used public cost measures for this process. These are cross-industry medians, not enterprise-only, and the process definitions differ between measures, so they should not be added together.
Three further figures are worth holding alongside those, because they describe the gap between a median performer and a good one:
- Manual journal entry share. APQC's top performers post between 0.75% and 6% of journal entries manually. The median across other participants is 25%. This is the widest single gap in the whole process.
- Cost per entry by automation level. IBM's record to report research reports cost per journal entry falling from around $1.73 to $1.07 as automation rises toward 95%, and finds that organizations with mature robotic process automation in general accounting run a 25% faster monthly close and a 38% lower cost per journal entry than lower-automation peers.
- Transactional time share. IBM also finds finance spends roughly half its time on transactional activity. That is the pool a cost program is actually drawing from.
A word of caution on one metric people ask for constantly: there is no reliable public median for cost per reconciliation. The scope varies too much between organizations. Calculate it from your own reconciliation labor, systems and overhead divided by reconciliations completed, and do not borrow someone else's number.
How to Calculate Your Own R2R Cost
You can size your R2R cost gap with four inputs, all of which you already have. The point is not precision to two decimal places. It is to find out whether you are near the median, well above it, or already good.
Step 1. Pull your annual general accounting cost. Take the fully loaded cost of the general accounting and reporting function: salaries and benefits, allocated systems cost, overhead, plus any outsourced or contractor spend. Include close-week overtime, which is usually sitting in a different cost center.
Step 2. Count your journal entries and reconciliations. Pull twelve months of journal entry volume from the ERP, split by system-generated and manual. Do the same for reconciliations completed, split by auto-matched and manually worked.
Step 3. Work out your three unit costs.
- Cost per journal entry = annual general accounting cost / annual journal entries
- Cost per $1,000 revenue = annual general accounting cost / (revenue / 1,000)
- Manual journal share = manual entries / total entries
Step 4. Compare against the table above and price the gap.
Here is what that looks like for a $500 million enterprise posting 4,000 journal entries a month.
Annual journal entry volume is 48,000. At APQC's $3.50 median, general accounting would cost about $168,000 against journal entries alone, and at $0.91 per $1,000 of revenue the function as a whole would benchmark at roughly $455,000. Against the broader R2R scope at $2.30 per $1,000, the whole cycle benchmarks around $1.15 million.
Now apply the manual share. At the 25% median, 12,000 of those 48,000 entries are posted by hand each year. Moving to the 6% top-performer band leaves 2,880 manual entries, which removes about 9,120 manual postings annually. At even fifteen minutes of fully loaded preparation, review and posting time per entry, that is roughly 2,280 hours a year, or a little over one full-time equivalent, released without touching headcount policy at all.
That calculation takes an afternoon, and it converts an abstract efficiency argument into a number a CFO can approve against. If your figures land well above the medians, the levers below are where to start. If they land below, your opportunity is probably in cycle time and risk rather than unit cost.
The Cost Levers, Ranked by Payback
Levers do not return money at the same speed, and the cheapest ones are usually the fastest. The ranking below is ordered by how quickly each typically pays back, not by how much total cost it can eventually remove.
The ordering matters more than any individual line. Running lever 9 before levers 1 and 2 is how organizations end up paying to automate an inconsistent process, which is a well-documented way to make it permanent.
1. Fix Journal Entry Policy Before You Buy Anything
The fastest money in R2R costs nothing to implement. Set a materiality threshold below which manual journal entries are simply not permitted, require automated journal entry templates for recurring accruals and allocations, and stop accepting intra-month adjustments that could wait for the next cycle.
This usually removes a third to a half of manual journal volume on its own, and it does it before any software decision. It also makes the automation that follows much cheaper, because you are automating a smaller, more consistent set of entries.
2. Standardize the Close Before You Automate It
Give every close task a single owner, a single deadline and a stated evidence requirement. Rationalize the chart of accounts where entities will tolerate it. Remove duplicate reconciliations, which are more common than most teams expect once someone actually lists them.
For multi-entity groups this is the harder half of the work, and it is worth doing deliberately. The practical approach to standardizing R2R across multiple entities is to converge on templates and calendars first and leave system consolidation for later, because template convergence returns money immediately and does not need a capital case.
3. Automate the Journal Entries That Repeat
Once policy has cut the volume and standardization has made the remainder consistent, automate what is left of the recurring set: accruals, depreciation, allocations, standard adjustments. Validate against ERP posting rules before submission rather than discovering failures after, because a rejected entry costs several times what a clean one does.
Keep approval routing and materiality rules in the workflow. Automation that removes the control along with the keystrokes produces a faster close that is harder to audit, which costs money back at year end.
4. Automate Reconciliations by Volume First
Start with the highest-volume, most rules-based reconciliations: bank, cash, clearing accounts, subledger to general ledger. Apply deterministic matching rules before anything more sophisticated, because most of the volume matches on amount, date and reference.
Certify low-risk accounts by policy rather than reviewing them individually. Reviewer time should concentrate on high-risk, high-value accounts, which is both cheaper and better control. Teams working through this sequence often find it easier to break up monthly reconciliation into smaller daily runs before automating, because it exposes which accounts are genuinely difficult.
5. Smooth the Workload With a Continuous Close
The peak-load premium is real money. A continuous close spreads matching, validation and documentation evenly across the month instead of concentrating it into the days when labor is most expensive and error rates are highest.
This is the lever that most directly removes overtime and contractor spend, and it tends to improve quality at the same time, because differences surface days after they occur rather than weeks. If you are not sure how much room you have, start by establishing how long month-end close takes today, broken down by task rather than in aggregate.
6. Work the Root Cause, Not the Exception
Every exception you resolve without fixing its cause will arrive again next month. Categorize exceptions by cause rather than by account, assign ownership for the top three categories, and track repeat rate as a metric in its own right.
This is slower to pay back than the automation levers, but it compounds, and it is the difference between an automated close that gets cheaper over time and one that plateaus.
7. Be Careful With the Operating Model Lever
Shared services and GCC migration genuinely reduce blended labor rates, and for enterprises operating across India, the Philippines and Malaysia the capability is close at hand. The condition is that the process must be standardized before it moves. Transferring an inconsistent close to a new team adds a handoff to a process that already had too many.
ERP and data layer consolidation sits at the end for the same reason. It returns the most eventually and the least soon, and it only works once the process it is consolidating has one shape.
The Cost Cuts That Backfire
Some of the most common R2R cost reductions create more expense than they remove, usually in a later period and a different budget line. These are worth naming before you commit to a program.
- Cutting headcount before standardizing the process. The work does not disappear with the people. It reappears as overtime, as contractors in close week, and as a slower close that delays reporting. Reallocating staff from transactional work to exception review is the version that holds.
- Applying risk-based reconciliation by account size instead of by risk. Small accounts can carry large risk. A threshold set on balance alone will certify away exactly the accounts where errors hide, and the saving is repaid with interest at audit.
- Offshoring an unstandardized close. You export the inconsistency and add a time zone to it. Standardize, then move.
- Buying automation before fixing the source data. A matching engine fed by unreliable extracts produces exceptions at speed. Data quality is a prerequisite, not a phase two.
- Measuring close days instead of close cost. It is entirely possible to shorten the close by spending more, through overtime and additional contract resource. If days are the only metric, that is what the organization will optimize for.
How to Tell If R2R Cost Is Actually Falling
Track unit cost, not total cost. Total cost moves with revenue, acquisitions and entity count, so it will not tell you whether the process itself got cheaper.
Four measures are enough, and all four should be baselined before the first change goes in:
- Cost per journal entry, calculated the APQC way, as total general accounting cost over entries processed. This is the headline number.
- Manual journal entry share, tracked monthly. The direction of travel here predicts the other three.
- Auto-match rate on reconciliations, split between deterministic and AI-assisted matching so you can see which is carrying the load.
- Close-week overtime and contractor spend, which is where the workload-smoothing levers show up and where they are usually invisible in a standard close report.
If cost per journal entry is flat while close days are falling, you are buying speed with labor rather than removing work. That is the pattern worth catching early. For the controls and risk side of the same program, the record to report automation framework covers how segregation of duties and audit evidence should be built into the automated workflow rather than bolted on afterward.
Before you set internal targets, check the measure definitions behind the benchmarks you are using. APQC's Open Standards Benchmarking measure set and IBM's record to report research both define the process scope they cover, and that scope may be wider or narrower than yours. A target borrowed from a benchmark that includes fixed-asset accounting will not hold if your R2R scope excludes it.
When Bluecopa Will Be the Right Choice for R2R Cost Reduction
Bluecopa fits enterprises where R2R cost is driven by transaction volume and system fragmentation rather than by headcount policy: typically $250 million and above in revenue, multiple entities, several source systems feeding the ledger, and a close that opens with a reconciliation backlog.
The structural difference is the data layer. Because order to cash, procure to pay and record to report run on one AI-native platform, transactions are matched continuously as they arrive rather than in a month-end sweep. The close does not start with a backlog, which removes the most expensive category of work in the table above instead of automating it.
Four SamyxAI agents carry the cost levers directly:
- Samyx Recon matches general ledger, bank, ERP and gateway transactions continuously at over 5 million records per hour with 97% to 99% accuracy, which is the lever on auto-match rate and reconciliation labor.
- Samyx Build applies policy-as-code materiality thresholds and approval routing to journal entries, which is the lever on manual journal share, enforced in the system rather than in a policy document.
- Samyx Narrate drafts variance commentary, removing a reliably underestimated block of analyst time at period end.
- Samyx Extract pulls data from supporting documents so reconciliation evidence does not have to be assembled by hand.
The outcomes map to the drivers rather than to speed alone. Purplle had more than 30 people on validations and reconciliations and book closure running 10 to 15 days late; after automating data ingestion and standardizing journal entries the team saw an 80% reduction in manual journal entries and a 50% faster month-end close. Porter, closing manually across seven verticals and 22 cities, cut manual reconciliation effort by 70% and closed six times faster. Both figures sit on the two drivers that carry most of the cost.
One thing to be clear about: Bluecopa is a finance automation platform that sits on top of your ERP. It handles reconciliation, continuous close and journal automation. It is not a statutory consolidation suite, an FP&A planning tool or a treasury system, and it is not an ERP replacement. If your R2R cost problem is actually a consolidation or planning problem, a different layer of the stack is where to look.
Teams still deciding which layer they need can compare the available record to report automation software before committing to a direction.
Frequently Asked Questions
1. How much can you realistically reduce R2R cycle cost by?
Organizations moving from median to top-quartile automation typically see cost per journal entry fall by around 38% and close cycle time by roughly 25%, based on IBM's cross-industry research.
2. What is the biggest cost driver in the record to report cycle?
Manual journal entries and manual reconciliations together account for most R2R labor cost, and the share of journal entries posted by hand is the single widest gap between median and top performers.
3. What does a journal entry cost to process?
APQC's cross-industry median for general accounting is about $3.50 per journal entry and $0.83 per line item, though the figure varies with transaction volume, entity count and automation level.
4. Should you standardize the close before automating it?
Yes. Automating an inconsistent process locks the inconsistency into the system, and standardization returns money immediately without needing a software budget or a capital case.
5. Is outsourcing R2R cheaper than automating it?
Outsourcing reduces blended labor rates but adds handoffs and governance cost, and it only works on a standardized process. Most enterprises get faster payback from policy and automation first.
6. How do you measure whether R2R cost is actually falling?
Track unit cost rather than total cost: cost per journal entry, manual journal share, reconciliation auto-match rate, and close-week overtime and contractor spend, all baselined before any change.
Book a demo
See Bluecopa run on your own close
70%
Faster month-end close
95%
Reduction in manual effort
30 min · your ERP · no slide deck
Benchmark
How your close compares
Spreadsheet-run close
11 days
Point tools
7 days
Bluecopa
4 days
Calculate your close time
30 min · your ERP · no slide deck