Key Takeaways
- ERP agility for accounts receivable comes down to four measurable dimensions: speed of cash application, scalability across volume and entities, visibility into credit risk, and adaptability to new payment channels.
- Native ERP AR modules are built for transaction recording, not for the volume, visibility, and workflow demands of a modern collections and cash application process, which is why they create rigidity as a business grows.
- Real-time cash application, AI-driven collections prioritization, and credit risk dashboards are the specific automation levers that close each gap.
- A phased rollout (data foundation, then a pilot, then full sync) gets you to full automation without disrupting the ERP your team already relies on.
- The clearest way to measure agility gains is a direct before/after comparison: invoice delivery speed, automated payment matching rate, and DSO impact.
Most finance teams don't discover their ERP's AR module is rigid until volume, entity count, or payment complexity outgrows it. The invoices still get sent, the cash still (eventually) gets applied, but every step takes a person, and every new entity or payment channel makes that person's job a little harder. That's what "ERP agility" actually means in an AR context, and it's worth defining clearly before jumping to fixes.
A quick overview: this guide defines ERP agility for accounts receivable as four measurable dimensions, walks through the specific automation levers that address each one, and lays out a phased plan for rolling automation in without disrupting the ERP you already run.
What Does ERP Agility Actually Mean for Accounts Receivable
"Agility" gets used loosely in most AR content, usually as a stand-in for "automation is good." It's more useful to break it into four specific, checkable dimensions:
- Speed: how quickly a payment is matched, applied, and reflected in your cash position, versus sitting in an unapplied-cash bucket for days.
- Scalability: whether your AR process holds up as transaction volume, customer count, or entity count grows, without requiring proportionally more headcount.
- Visibility: whether your team can see credit risk, promise-to-pay status, and aging in real time, or only after a manual report is pulled together.
- Adaptability: whether your AR process can absorb a new payment method, currency, or business unit without a re-implementation project.
A native ERP AR module that scores poorly on these four dimensions is the rigidity this guide is addressing. Automation, layered correctly, is what moves the needle on each one.
Where Native ERP AR Modules Create Rigidity
Most ERPs were built primarily as systems of record, not workflow engines, and their native AR functionality reflects that. The recurring gaps:
- Manual remittance capture. Payment details arriving by email, portal, or paper check often require manual entry before they can be matched to an invoice.
- Siloed credit data. Credit risk information frequently lives outside the ERP entirely, in spreadsheets or a separate credit system, disconnected from live AR activity.
- No promise-to-pay tracking. Native modules rarely capture collector notes, customer commitments, or dispute status in a structured, reportable way.
- Limited reporting depth. Native dashboards typically stop at aging summaries, without drill-through into deduction reasons or collector productivity.
Each of these is a specific, fixable gap, not a reason to replace the ERP itself, which is the point of framing this as automation layered on top rather than a migration.
How to Automate Cash Application to Speed Up Your ERP
Cash application is usually the single biggest speed lever. Automated remittance aggregation pulls payment details from email, EDI, and customer portals into one place, and AI-driven matching engines reconcile that data against open invoices without manual line-item checking. Well-implemented cash application automation can push auto-match rates up to the 90 to 95% range, compared to a largely manual process that leaves a meaningful share of cash sitting unapplied at any given time.
How to Automate Collections Prioritization Inside Your ERP
Once cash is applying quickly, the next bottleneck is usually collections. AI-driven worklist prioritization ranks which accounts a collector should call first based on risk, balance, and payment history, instead of a flat, alphabetical, or oldest-first list. Automated dunning sequences handle the routine reminder cadence entirely, freeing collectors to spend their time on the accounts that actually need a human conversation.
How to Get Real-Time Credit Risk Visibility Without Leaving Your ERP
Credit risk monitoring dashboards, integrated via API directly into the ERP, close the visibility gap by surfacing customer credit exposure, payment behavior trends, and risk scoring in the same place your team already works, rather than requiring a separate system or a manually updated spreadsheet.
How to Scale AR Automation Across Multiple Entities and ERPs
The adaptability dimension is where native ERP AR tools struggle most. A module built for one entity on one ERP instance rarely extends cleanly to a multi-entity, multi-ERP environment, which is exactly the scenario growing or acquisitive companies run into. AR automation built to consolidate across entities and ERPs, rather than automating just one instance at a time, is what actually solves for this rather than pushing the same rigidity problem down to each new entity as it's added.
How to Roll Out AR Automation in Phases Without Disrupting Your ERP
Automating AR doesn't need to happen all at once, and trying to do it all at once is usually where rollouts stall. A phased approach works better in practice:
- Phase 1: Data Foundation. Audit customer data quality and standardize payment terms inside the ERP before introducing any automation on top of it. Automation built on inconsistent underlying data just automates the inconsistency faster.
- Phase 2: Pilot Testing. Launch automated invoicing and reminder workflows with a small, representative subset of customers, so any issues surface on a manageable scale rather than across the entire book at once.
- Phase 3: Full Sync. Roll out AI-driven cash application and predictive collections worklists at full scale, once the pilot has validated the workflow and the underlying data foundation is solid.
Traditional ERP AR vs. Automated AR: What Actually Changes
A direct before-and-after comparison makes the impact concrete rather than abstract:
- Invoice delivery: manual print, mail, or individual email under a traditional process, versus instant batch electronic delivery once automated.
- Payment matching: manual line-item checking under a traditional process, versus up to 95% automated AI matching once automated.
- DSO impact: tracking at your baseline industry average under a traditional process, versus typically reduced 15% to 30% once cash application and collections are automated.
How to Measure ERP Agility Gains From AR Automation
The comparison above is a useful starting benchmark, but the metrics that matter for your own business are the ones you track before and after rollout: DSO reduction over a comparable period, the auto-match rate on cash application, and the average days to resolve a deduction. Grounding the automation initiative in these specific, measurable numbers, rather than a general productivity claim, is what makes the ROI case defensible to finance leadership.
How Bluecopa Extends ERP Agility With AR Automation for Enterprise Finance Teams
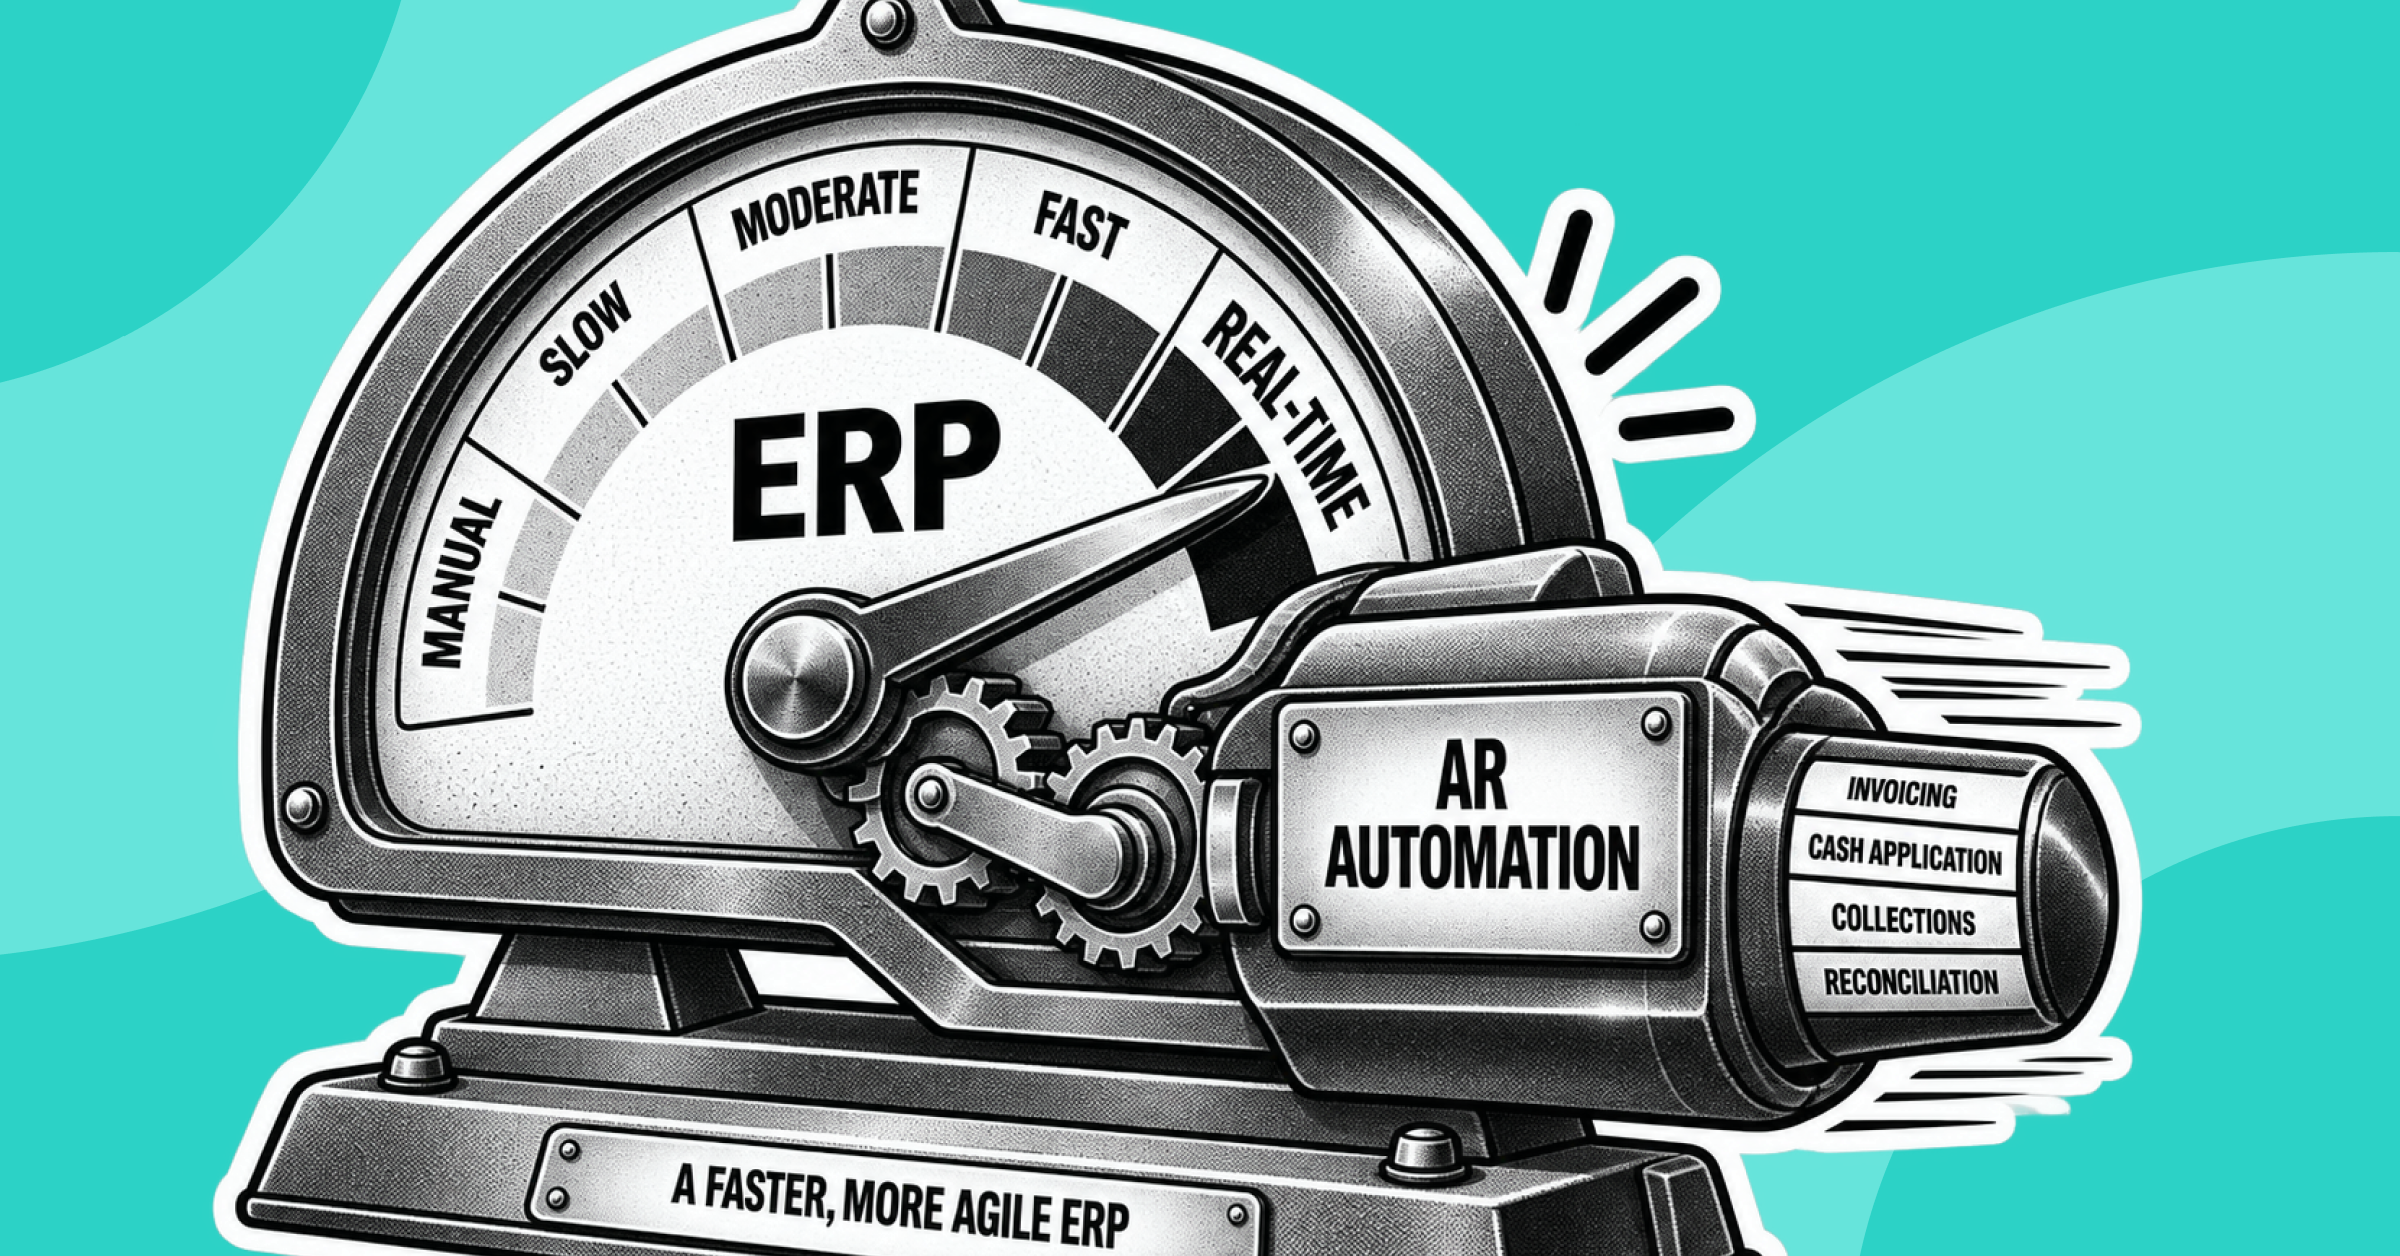
Bluecopa's AI-native finance operations platform layers directly onto your existing ERP rather than replacing it, automating cash application, collections prioritization, and credit risk visibility across every entity in real time. For enterprise finance teams running AR across multiple business units, currencies, or ERPs, that means the four agility dimensions covered above, speed, scalability, visibility, and adaptability, improve without a disruptive ERP migration or a rebuild of processes your team already knows.
Frequently Asked Questions
1. What does ERP agility mean for accounts receivable?
It refers to four measurable dimensions: how quickly cash applies, how well the process scales with volume and entities, how much visibility your team has into credit risk and aging, and how easily the process adapts to new payment methods or business units.
2. Do I need to replace my ERP to fix AR rigidity?
No. Most of the rigidity comes from gaps in the ERP's native AR module, which automation layered on top of the ERP addresses directly, without a migration.
3. How much can AR automation improve DSO?
Typical reported reductions run 15% to 30%, though the actual impact depends on your starting process and how much of cash application and collections you automate.
4. What's the right first step for automating AR inside my ERP?
Start with a data foundation phase, auditing customer data and standardizing payment terms, before introducing any automation. Automation layered on inconsistent data compounds the inconsistency rather than fixing it.
5. Can AR automation work across multiple ERPs?
Yes, when the automation platform is built to consolidate across entities and ERPs rather than automating a single instance at a time, which matters most for growing or multi-entity organizations.