Key Takeaways
- Accrual automation uses software to identify and post expenses earned in a period but not yet invoiced, replacing manual spreadsheet work and reducing month-end close time.
- Six core steps make up a typical automated accrual workflow: data collection, estimate calculation, completeness checks, human approval, ERP posting, and automated reversals.
- Five main accrual types are handled automatically: GRNI, contract-based services, payroll and benefits, travel and expense, and recurring operating costs.
- Audit-ready documentation is produced at the journal entry level, with source data, calculation worksheets, and approval history attached to every entry.
- Month-end close shortens when accruals run continuously throughout the period rather than as a manual exercise in the last few working days.
- Indian finance teams face specific complexity from GST invoice timing gaps, Ind AS 37 distinctions, and TDS interaction at the accrual entry level, all of which well-configured automation handles systematically.
What Is Accrual Automation?
Accrual automation uses software and AI agents to identify expenses or revenues earned in a period but not yet billed, calculate the amount to recognize, post the journal entry to the ERP, and schedule the reversal for the following period. It pulls from purchase orders, goods receipts, contracts, invoices, and payroll data, so finance teams don't need to reconstruct those records from scratch each month.
The accounting principle underneath it is straightforward. Under accrual accounting, revenue and expenses are recognized when they are earned or incurred, not when cash moves. Automation applies that principle consistently across entities and systems, using configured rules rather than manual estimates.
The practical benefit for controllers is earlier, cleaner visibility into period-end liabilities. Instead of discovering missed commitments on working day 2 or 3, the system surfaces them continuously as source data arrives. For groups managing multiple entities, it also means the same methodology applies consistently across all books rather than each entity running its own spreadsheet approach.
Why Manual Accruals Break Down
Manual accrual processes work reasonably well when transaction volumes are low and source data lives in one system. They break down as the business grows and as purchasing, receiving, expenses, and accounting operate in separate tools.
Open POs without goods receipts. Finance can see that a purchase was approved but not whether goods or services were actually received, how much was delivered, or which period the cost falls in. Teams often estimate from the remaining PO balance, which can overstate or understate the accrual.
Unsubmitted expense reports. Employees incur travel, meals, and other costs before period end but submit reports days later. Finance rarely gets a complete picture of T&E exposure in time to accrue accurately.
Data scattered across systems. Accrual support sits across procurement software, email, contract repositories, receiving records, and the ERP. Accountants have to map identifiers, reconcile formats, and resolve differences before they can build an entry. A finance team working across five or six systems spends most of the accrual process on data collection, not accounting judgment.
Compressed review time. When the first four or five working days are consumed by data gathering, controllers have little time left to investigate unusual balances or review high-value estimates before the books close.
The pattern that surfaces repeatedly in enterprise close processes: finance teams run a parallel manual process alongside whatever automation exists, because they don't trust that the system caught everything. That parallel process consumes the time the automation was supposed to free up. One finance group managing six legal entities on Oracle Fusion found that journal voucher adjustments were tracked entirely outside the ERP in spreadsheets before posting, requiring a manual reconciliation against the trial balance before every close.
How Accrual Automation Works
A typical automated accrual workflow runs through six steps.
- Data Collection. The system gathers open purchase orders, goods received not invoiced (GRNI) records, contracts, recurring vendor commitments, expense reports, and payroll data from the ERP and connected systems. The goal is to surface everything that might represent an incurred cost before the invoice arrives.
- Estimate Calculation. Configured accounting rules determine which items qualify, which period they belong to, the materiality threshold, and the calculation method. A GRNI accrual uses the received quantity and the PO unit price. A contract-based accrual uses the service period and contracted rate. The system calculates a proposed accrual amount for each item using the best available source data.
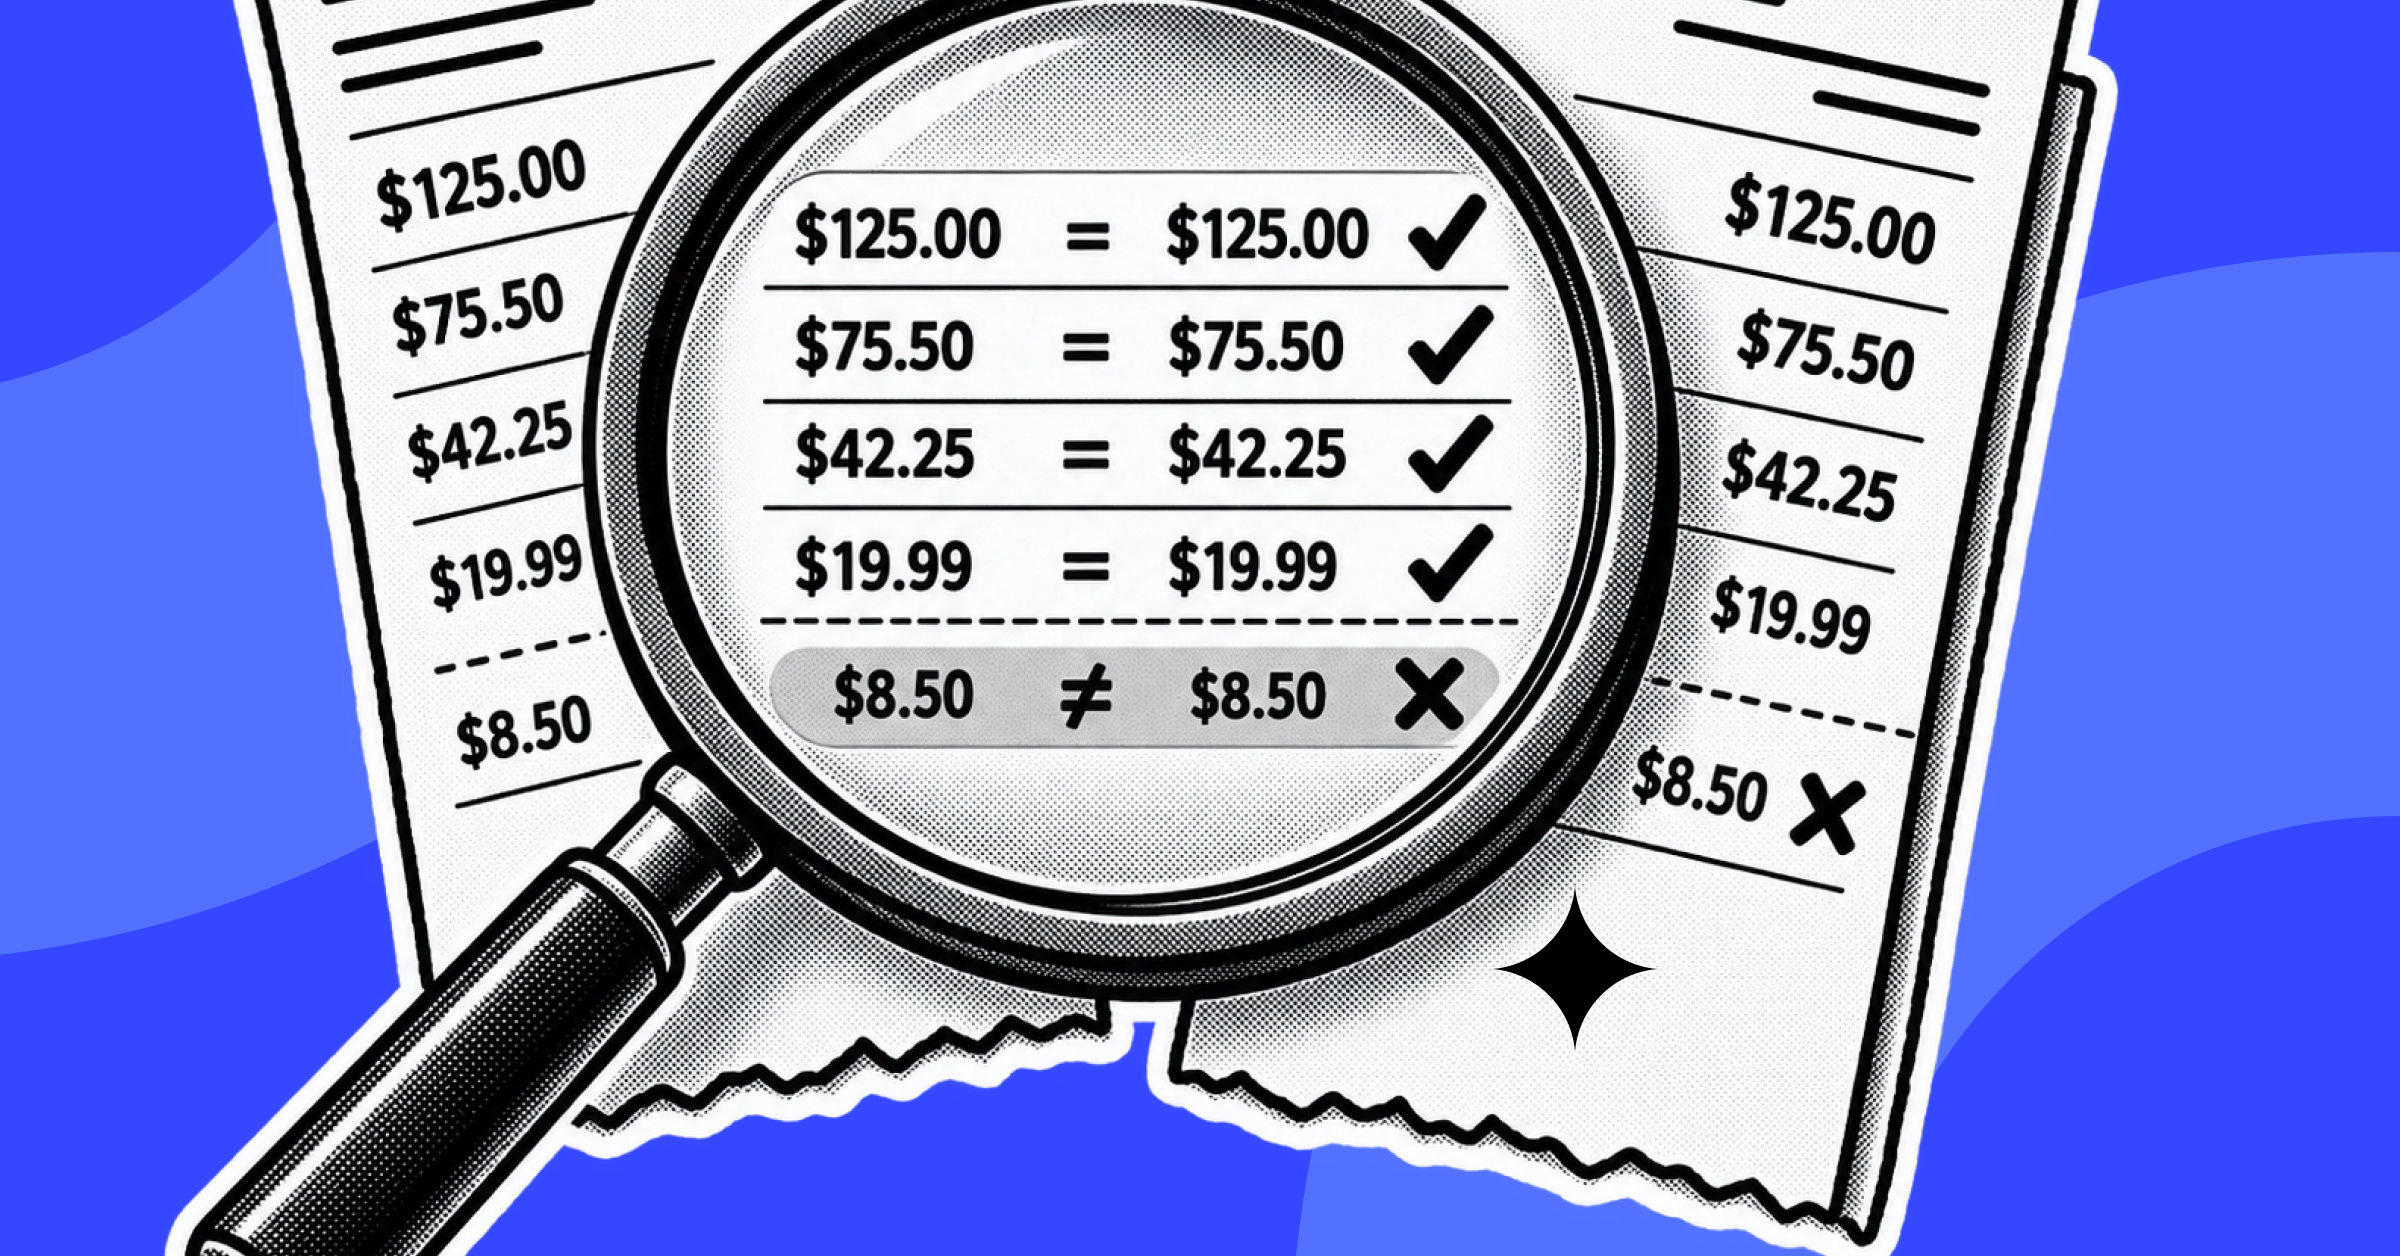
- Duplicate and Completeness Checks. Before entries are drafted, the system cross-references its output against AP inboxes and already-posted invoices to prevent double-counting. It also checks for known recurring vendors missing from the current period's run, flagging potential omissions for reviewer attention.
- Human Approval and ERP Posting. Draft entries are routed to the controller, accounting owner, or AP lead based on configured thresholds by amount, category, and entity. Reviewers can inspect the underlying PO, receipt, contract, or other supporting record before approving, adjusting, or rejecting. Once approved, the system posts the entry to the ERP with the correct legal entity, GL account, cost center, and accounting dimensions.
- Automated Reversals. The system schedules the reversal for the first day of the next accounting period without requiring manual intervention. When the actual invoice posts, the system compares the invoice amount against the estimate and records any difference as a variance adjustment.
- Variance Monitoring. Over subsequent periods, the system tracks how estimates compare against actuals by vendor and accrual category. Finance can use this data to refine calculation rules rather than adjusting entries by hand each month.
Automation does not remove accounting judgment from the process. It gives reviewers a more consistent calculation method, a traceable path from the journal entry to its supporting records, and more time to focus on the entries that actually warrant scrutiny.
Types of Expense Accruals
The scope of what gets automated depends on the available source data and the platform's configuration. The five most common categories are:
- GRNI accruals (Goods Received, Not Invoiced). Items physically received before period end when the supplier invoice hasn't yet been processed. The accrual is based on the PO unit price and the quantity recorded in the receiving system.
- Contract-based accruals. Services delivered under a contract but not yet invoiced, including consulting, legal services, software licenses, and maintenance agreements. The calculation uses the contract terms and the share of the service period falling within the current accounting period.
- Payroll and benefits accruals. Wages, bonuses, payroll taxes, and benefits earned during the period but paid after period end. These require payroll system data and usually sit outside the procurement and AP workflow.
- Travel and expense accruals. Costs employees incurred before period end but haven't yet submitted as expense reports, or reports submitted but not yet processed. Reliable T&E accruals depend on timely data from the expense platform or corporate card system.
- Recurring operating accruals. Utilities, insurance, rent, interest, and professional fees where the expense is predictable in amount and timing. Rules-based automation handles these well because the estimate rarely changes significantly from period to period.
One category often confused with accruals: prepaid expenses. A prepaid records cash paid before the company consumes the benefit. An accrued expense records a cost incurred before payment or invoicing. Both arise at period end, but the accounting treatment and the source data differ. Automation may support both, but they should be configured as separate processes with separate calculation logic.
Key Benefits of Accrual Automation for Finance Teams
Faster month-end close. Accruals that run continuously throughout the period don't create a data-collection bottleneck in the last few working days. Controllers start reviewing proposed entries on day 1 of close rather than spending that day chasing source records from department heads and vendors.
Audit-ready documentation. Every journal entry carries an attached calculation worksheet, the source data it was derived from, the approval trail, and the variance against the final invoice. Auditors can trace any accrual entry from the GL back to its originating PO, receipt, or contract without the finance team pulling records manually at audit time.
Fewer errors from manual rekeying. Manual accrual processes introduce errors at three stages: data collection, formula construction, and ERP entry. Automation handles all three, reducing the risk of miscoded dimensions, transposed amounts, and missed recurring vendors.
Better visibility into committed spend. Because the system runs on live source data, the CFO and controller see an up-to-date picture of incurred liabilities throughout the month, not just at close. Decisions made during the period reflect current obligations rather than the previous month's actuals.
Consistent methodology across entities. Multi-entity finance groups benefit most. The same rules apply across every legal entity and ERP instance, so the accrual basis is comparable across the consolidated books and the CFO can rely on numbers without knowing which entity ran a more conservative or aggressive estimate that month.
Accrual Automation and the Month-End Close
Accruals sit at the intersection of accounts payable and the financial close. In most finance teams, they are treated as a close activity: something that happens in the last few working days of the period. That framing creates a time pressure that manual processes can't absorb well.
Automation shifts accruals from a close activity to a continuous process. Source data is collected throughout the month. Rules are applied as new POs are raised, receipts are recorded, and contracts advance. By the time the period ends, most of the calculation work is already done. Close becomes a review and approval exercise, not a data-collection exercise.
This has a compound effect on journal entry automation and close task management. When accruals feed into the JE workflow automatically, controllers don't need to manually queue accrual entries alongside other period-end adjustments. The entries arrive pre-calculated, pre-sourced, and ready for review.
For teams managing balance sheet reconciliation, clean accruals also reduce the number of open items on the accrued expenses account at month end. That account is consistently one of the most reconciliation-intensive on the balance sheet, and a significant share of the open items trace back to accruals that were estimated differently from the invoice that eventually settled them. Better upstream estimation shrinks the reconciliation queue before it forms.
Accrual Automation in the Indian Context
Indian finance teams face a set of accrual-specific challenges tied to the local tax and regulatory environment. Spreadsheet-based processes handle these inconsistently. Well-configured automation handles them systematically.
GST invoice timing and ITC eligibility. Under India's GST framework, input tax credit on a purchase can only be claimed once the supplier has filed their GSTR-1 and the credit appears in the buyer's GSTR-2B. In practice, a vendor can deliver services in March, but the GST ITC may appear in GSTR-2B only in April after the supplier files. The P&L expense belongs in March under Ind AS, but the ITC claim is deferred. Manual accrual processes frequently conflate the two: either deferring the full expense accrual or attempting to claim ITC before it's reflected in GSTR-2B. Accrual automation should track both separately, recognizing the Ind AS expense accrual in the correct period and recording the ITC as a deferred recoverable until the GSTR-2B confirms it.
Provisions vs accruals under Ind AS 37. Ind AS 37 (Provisions, Contingent Liabilities and Contingent Assets) draws a distinction between provisions, which involve uncertainty in timing or amount, and routine accruals for goods or services received but not yet invoiced. GRNI and recurring service accruals are predictable and can be automated. Provisions that require management judgment, including litigation estimates, warranty provisions, and restructuring costs, cannot be automated without explicit review controls. Finance teams need accrual systems configured to distinguish between the two, routing provisions to management review while automating the high-volume routine categories.
TDS interaction at the accrual entry level. Under Sections 194J (professional services, typically 10%) and 194I (rent), TDS liability arises at the point of credit, which includes accrual, not just payment. A correctly structured accrual entry for professional services has three lines: debit Expense, credit Accrued Expense (net of TDS), credit TDS Payable. Manual processes often post a simple two-line entry and handle TDS at the payment stage. This creates a TDS payable that isn't visible until payment processes, which causes discrepancies during quarterly TDS return filing. Automating the TDS split at the accrual stage gives the finance team an accurate TDS payable position throughout the quarter.
March 31 year-end concentration. India's fiscal year ends March 31. Year-end close, statutory audit requirements, and TDS annual reconciliation all converge in the same window. Finance teams running manual accruals experience the greatest time pressure in mid-to-late March, exactly when auditors are also requesting information. Automating the accrual process reduces the volume of manual work in that window and gives the audit team a supported, traceable set of accrual entries from day one of the audit rather than reconstructed documentation.
Frequently Asked Questions
1. What is the difference between accrual accounting and accrual automation?
Accrual accounting recognizes revenue and expenses when earned or incurred. Accrual automation is the software that identifies, calculates, posts, and reverses those entries without manual spreadsheet work.
2. What are the main types of expense accruals that can be automated?
The five most common types are GRNI, contract-based service accruals, payroll and benefits, travel and expense, and recurring operating accruals for predictable costs like utilities and rent.
3. Does accrual automation remove the need for accounting review?
No. Data collection, calculation, posting, and reversals can be automated. Material or unusual entries should route to controller review based on configured amount and category thresholds.
4. How does accrual automation connect to the ERP?
Approved entries go to the ERP with the required entity, GL account, and dimensions. Integration can be real-time, batch, or file-based depending on the ERP and control requirements.
5. What is the difference between an accrual and a prepaid expense?
An accrued expense records a cost incurred before the invoice arrives. A prepaid records cash paid before consuming the benefit, then expenses it over the applicable periods.
6. How should Indian companies handle TDS when automating accruals for professional services?
Under Sections 194J and 194I, TDS liability arises at accrual, not just payment. A correctly automated entry credits the vendor net and TDS payable as two separate lines in the journal entry.
Editorial Note
Last Reviewed: October 2026. Ind AS references in this article are based on standards notified under the Companies (Indian Accounting Standards) Rules and as published by the Institute of Chartered Accountants of India (ICAI).
Book a demo
See Bluecopa run on your own close
70%
Faster month-end close
95%
Reduction in manual effort
30 min · your ERP · no slide deck
Benchmark
How your close compares
Spreadsheet-run close
11 days
Point tools
7 days
Bluecopa
4 days
Calculate your close time
30 min · your ERP · no slide deck